Plan the years
your portfolio must fund.
Clear thinking on retirement income, Social Security, tax sequencing, and the decisions that become permanent once the paycheck stops.
Latest insights
Nine concise, practical conversations for executives and families making the transition from accumulation to income.
The Retirement Plan You Built Deserves a Finish Line
Why beneficiary designations, trusts, tax strategy, and attorney coordination belong inside the same retirement plan—not in separate silos.
Read insight →
AI and Retirement Planning
What AI-driven wealth management reveals about the difference between investment management and a written retirement income plan.
Read insight →
Is Social Security a Scam?
Claiming Social Security at 62 is more than a returns decision. Consider longevity, taxes, survivor benefits, and household cash flow.
Read insight →
You’re Handed Your Severance Notice—Can You Respond Like This?
A severance notice at 61 felt like a retirement disaster. Complete retirement modeling revealed an unexpected Roth conversion opportunity.
Read insight →
Do Americans Decide Their Retirement Age/Date Anymore?
Restructuring, buyouts, AI, and severance can move a retirement date. The math should exist before employment uncertainty arrives.
Read insight →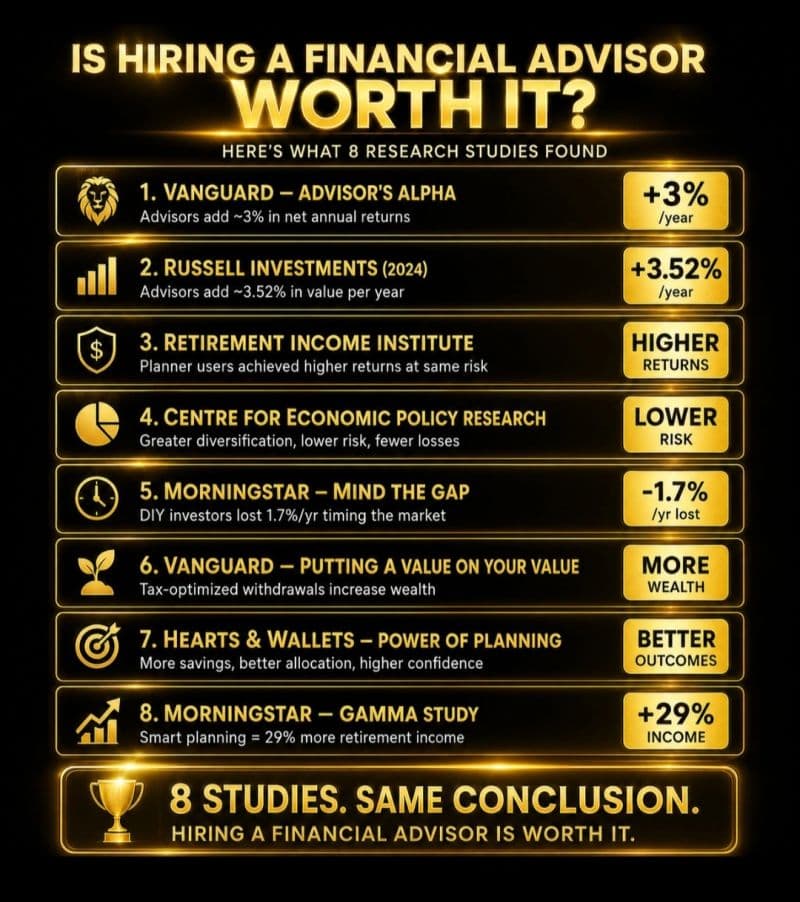
Is Hiring a Financial Planner Worth It?
Research measures the value of advice during accumulation. Near retirement, income, tax, and withdrawal sequencing require a different discipline.
Read insight →
We Found $127K More Social Security Income
A coordinated Social Security analysis for a married couple revealed a hypothetical $127,000 improvement in lifetime household income.
Read insight →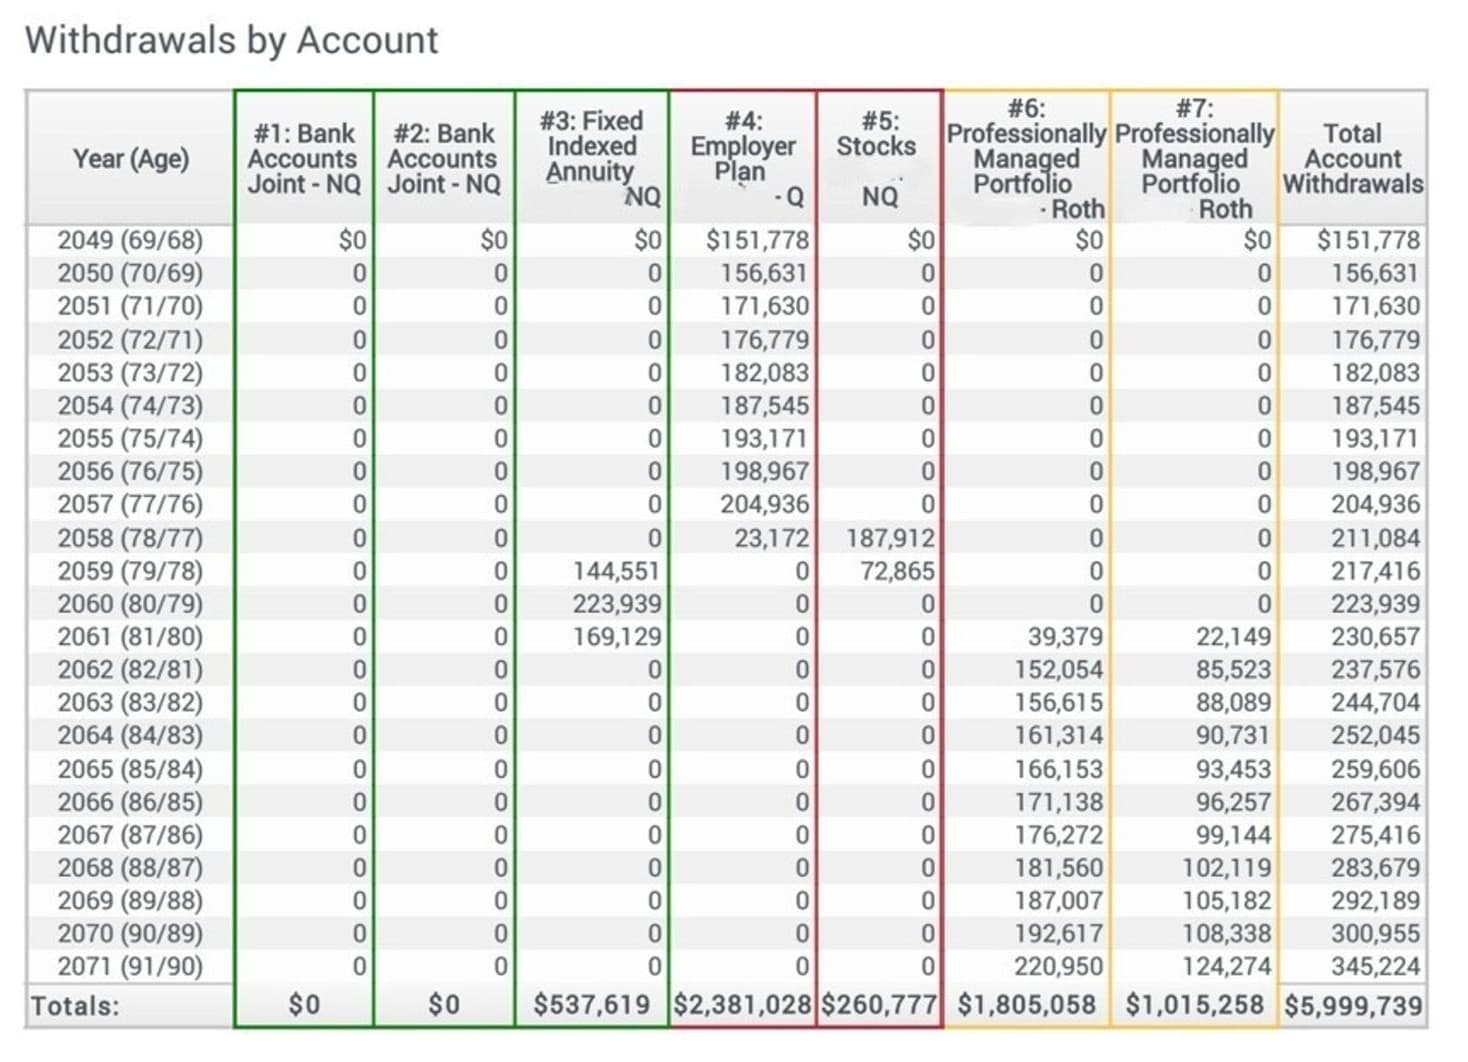
Let’s Compare Retirement Income Strategies
A retirement income plan determines the order in which accounts fund spending—and accounts for the tax consequence of every choice.
Read insight →
Social Security Is a 60% Pay Cut?!
Social Security replaces only part of pre-retirement earnings. A durable retirement plan needs income beyond one government benefit.
Read insight →Six decisions, worked through
Longer pieces that take one retirement income decision from the question to the answer, with a worked example and the sources.
Deferred Compensation: Navigating the Hidden Tax Trap
Non-qualified deferred compensation is taxed at vesting for FICA and at distribution for income tax, on a schedule you locked in years before retirement.
Can You Retire at 57? A Framework for Senior Executives
Five variables decide whether retiring at 57 works: healthcare, penalty-free access, the Social Security gap, portfolio longevity, and the conversion window.
RMD Exposure: What Your 401(k) Balance Really Costs You
How Required Minimum Distributions turn a large 401(k) balance into a forced tax event at 73 or 75, and multi-year strategies that shrink it before it arrives.
The Executive’s Complete Guide to Roth Conversion Strategy
How the years between your last paycheck and RMDs at 73 or 75 open a tax planning window, and how executives use it to convert pre-tax savings at lower rates.
Social Security Timing: A $100,000+ Decision
Delaying Social Security to 70 and coordinating both spouses’ claiming ages can be worth more than $100,000 in lifetime household income for a couple.
Withdrawal Sequencing: The Order That Changes Everything
The order you draw from taxable, tax-deferred, and Roth accounts shapes your tax bracket, your Medicare premium, and your Social Security tax bill every year.
The Executive’s Framework for Retirement Income Mastery
The three essays from the homepage, at full length, with the mechanics, the counter-arguments, and the sources behind each.
Why the First 10 Years of Retirement Are the Most Important Tax Planning Window of Your Life
The years from your last paycheck to your first RMD are often your lowest-income years in decades. What that window makes possible, and what closes it.
The Four Financial Challenges Unique to Executive Retirement, and How to Solve Each One
Deferred compensation timing, concentrated stock, the pension lump sum decision, and the years before Medicare. Four problems mass-market retirement advice does not cover.
Building a Retirement Income Architecture That Lasts 30 Years
An income architecture is more than a withdrawal rate. Four structural pieces built to make a paycheck last three decades, and what each one protects against.
Prefer to watch or listen?
Robert publishes short videos and podcast conversations on the same topics. Each one has a written page here too.
Ready to Build Your Retirement Income Roadmap?
A complimentary 30-minute consultation to assess your retirement readiness and identify your highest-value planning opportunities.
No sales pitch. No product recommendations. A genuine conversation about your retirement readiness.